Norma Market Risk
Overnight aggregation answers the questions anticipated the night before. Norma Market Risk re-aggregates the full portfolio on demand, so any question is answered in real time.
Bring the vectors your existing engine produces; your models stay in place and the aggregation is live.
Desk, book, trader, product, currency, counterparty, any dimension and any filter, recomputed in real time on a perimeter of tens of millions of transactions.
VaR, expected shortfall, standalone and incremental measures, P&L attribution and explain; FRTB standardised-approach capital by desk and risk class from the sensitivities, with the default risk charge and the residual risk add-on; the internal-model aggregation across liquidity horizons and the attribution tests on the same vectors.
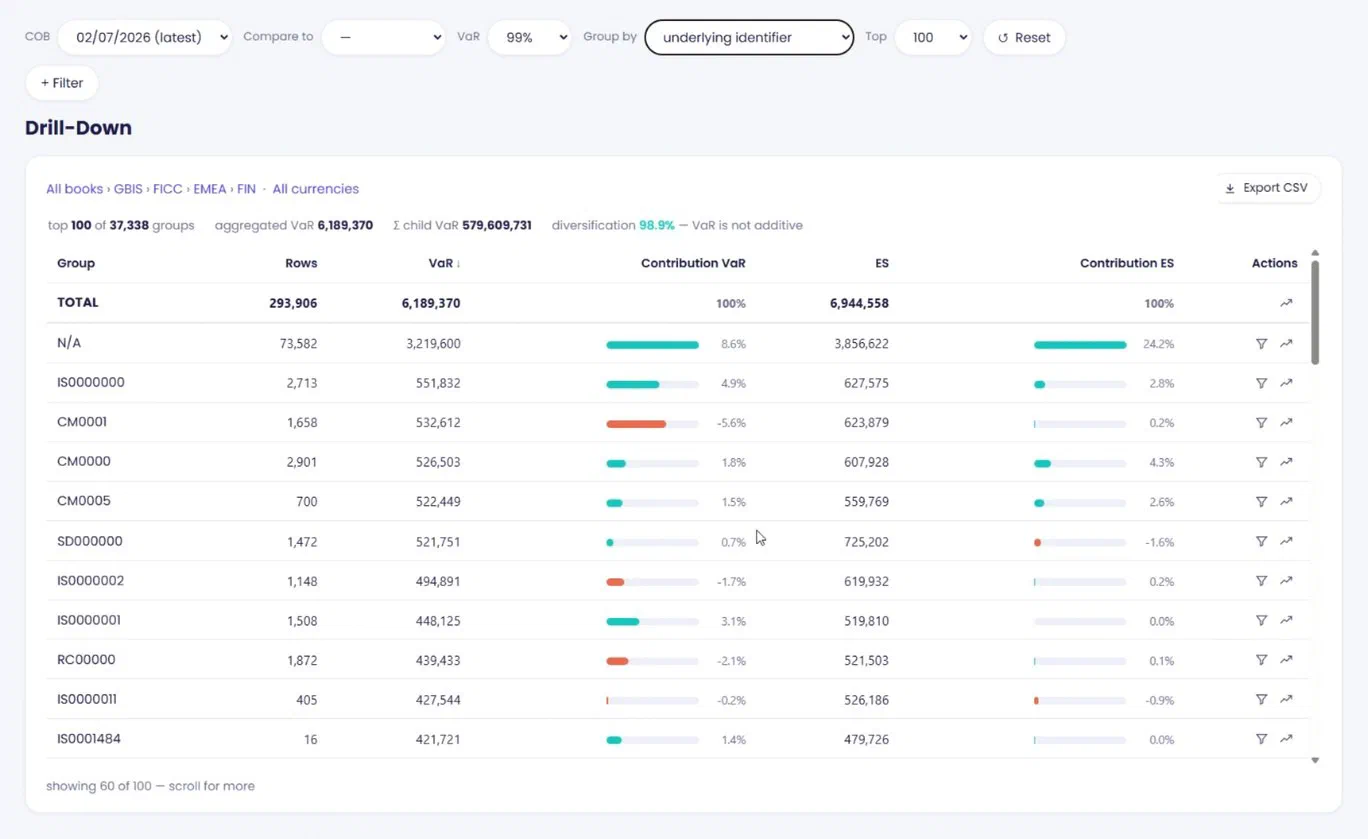
VaR and expected shortfall by book, desk and underlying, each with its contribution, recomputed as you move through the hierarchy.
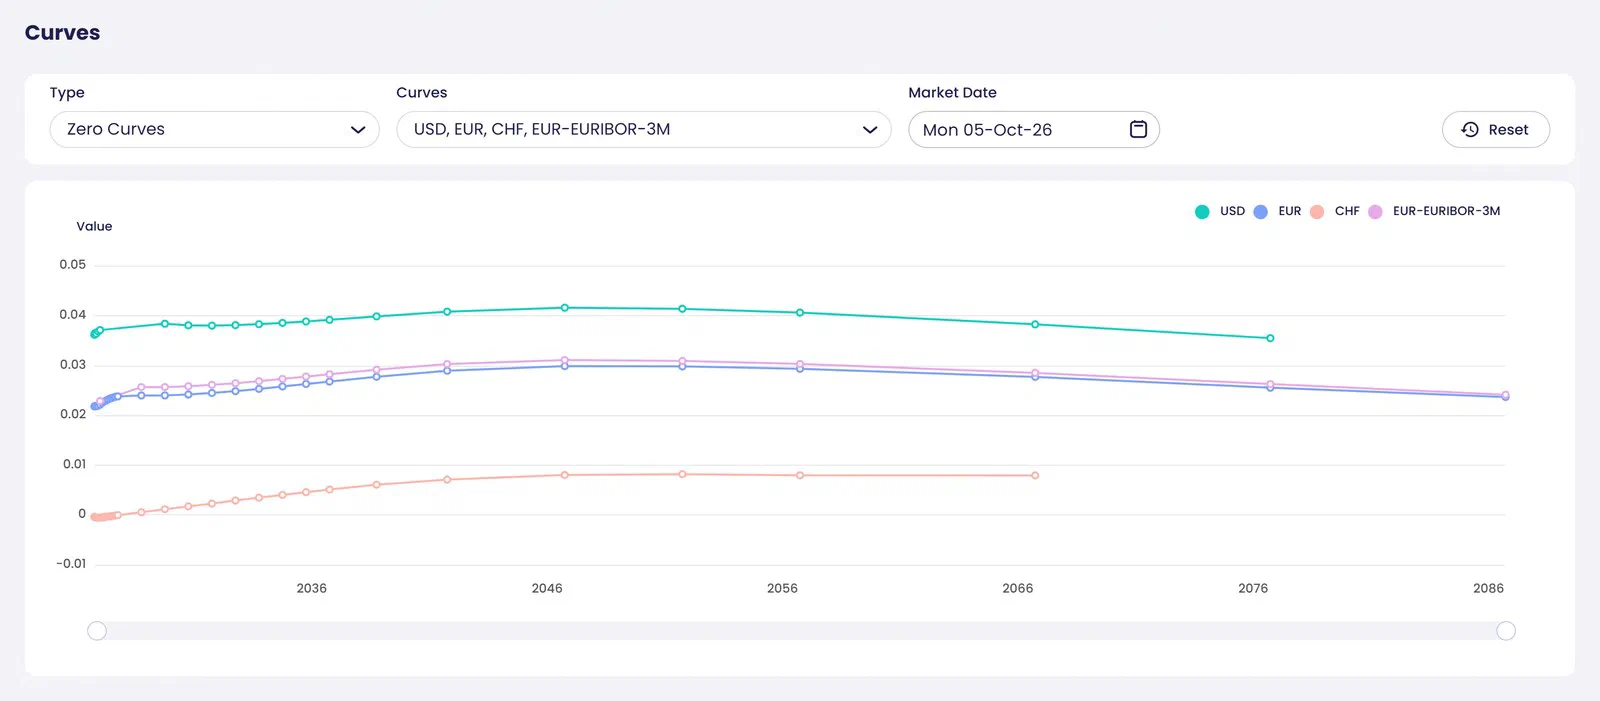
Zero curves by currency as of any market date, with the shock scenarios that apply to them, shared with pricing, capital and exposure.
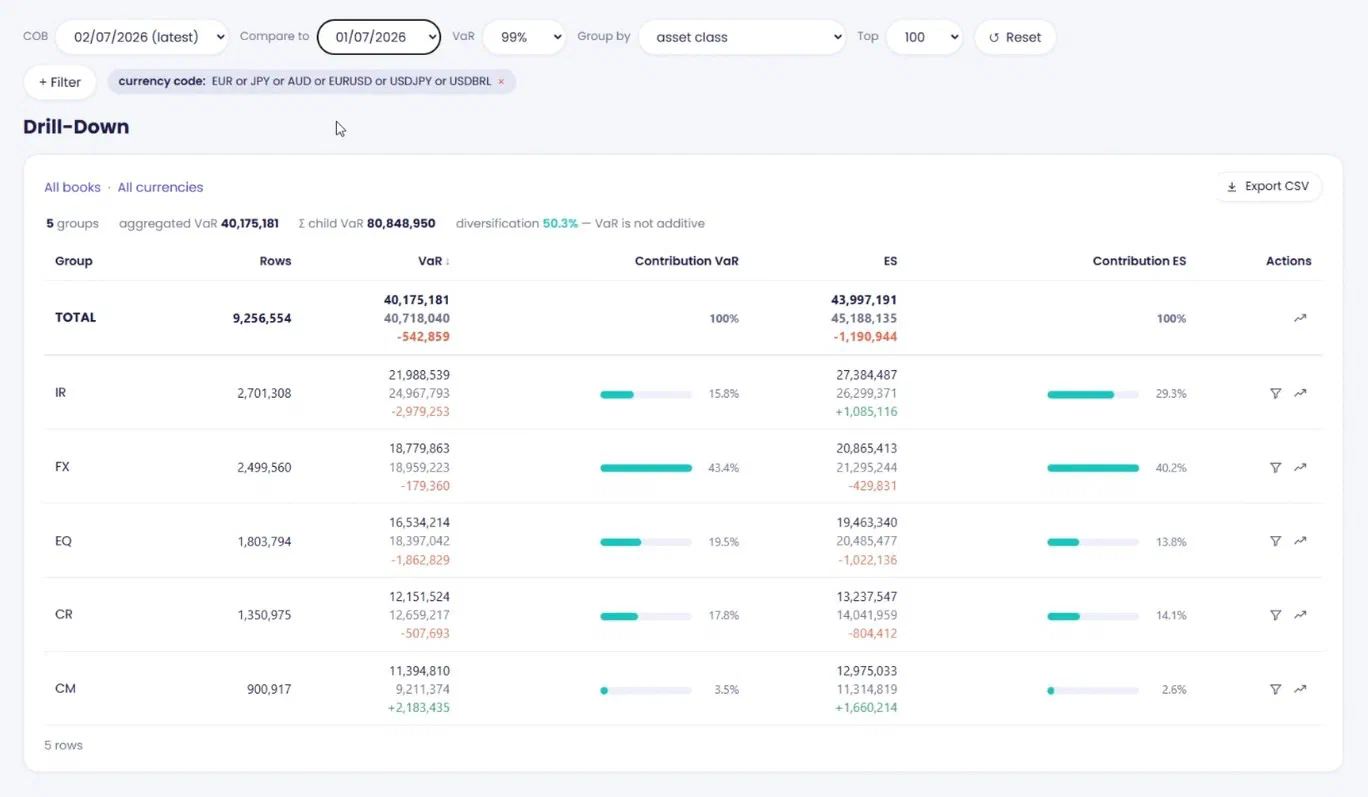
VaR and expected shortfall grouped by asset class across two dates, with a currency filter; the history of any book sits above its drill-down.
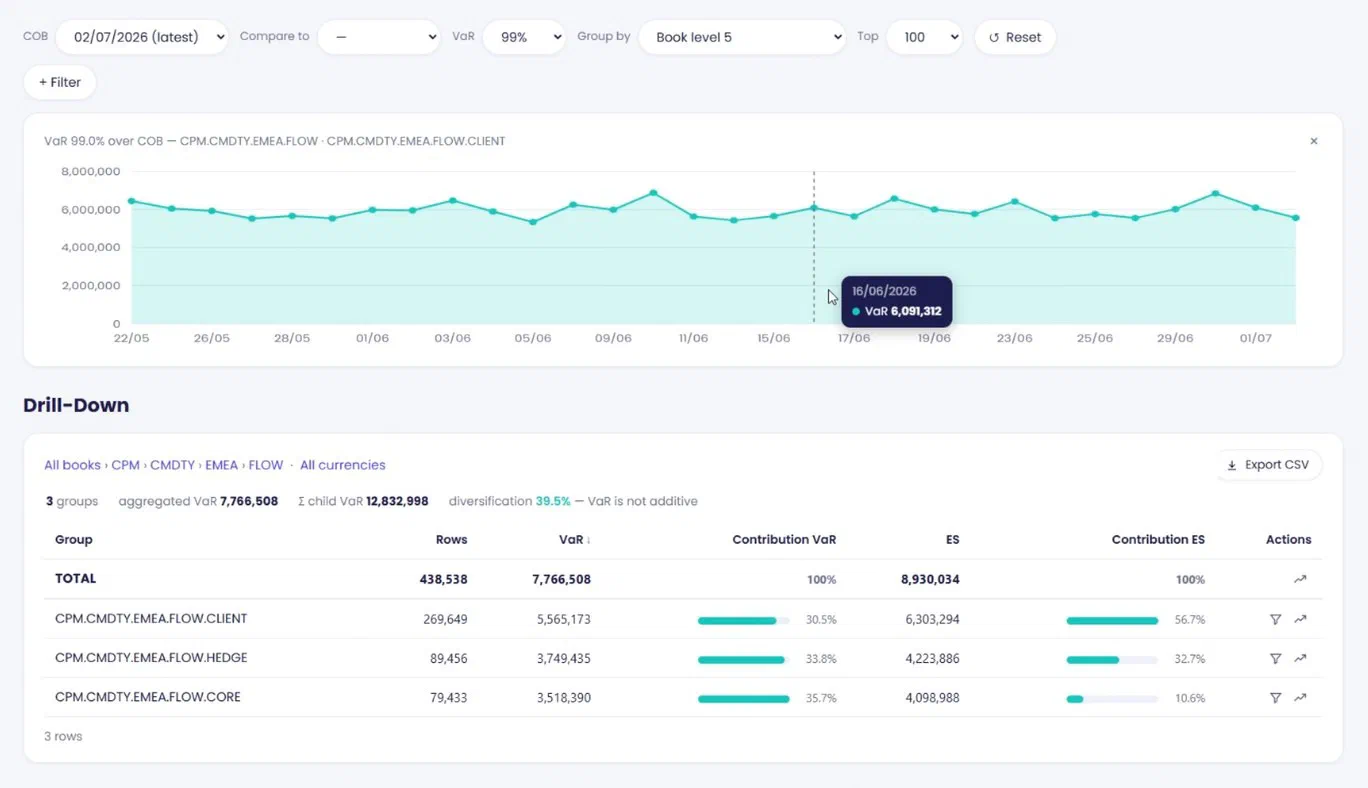
VaR over time for a selected book, with the sub-books underneath; a day that stands out is one click from its underlyings.
The standardised approach from the sensitivities: capital by desk and risk class, with the default risk charge and the residual risk add-on, recomputed as the book changes. The internal-model approach from the P&L vectors: expected shortfall aggregated across liquidity horizons, and the attribution tests at desk level.
FRTB applies in the EU from 2027, in the UK from 2027 for the standardised approaches and 2028 for internal models, and in the US on a date still to be set. Standardised-approach capital from the sensitivities, and desk-level expected shortfall and P&L attribution tests on the same vectors as VaR, on your own book.
Your own P&L vectors, aggregated live, in a demo.
Request a demo