Platform
Pricing, capital, exposure and market risk run on one engine with one set of models and market data. The desk, the capital team and risk work from the same numbers, computed when they ask, not the night before.
Every module runs on the Norma Platform: the Norma Core engine, the analytics dashboards, an API that exposes every function programmatically, market-data ingestion and validation, hosting or deployment in your tenancy, support and upgrades.
In
Norma Core
Out
Pre-trade, intraday, end of day and regulatory reconcile by construction: same models, same market data, same engine.
What-if, stress and drilldown are questions, not projects.
Full sensitivities on the whole book become routine rather than a project. That is what makes SA-CVA an option, and what-if a question rather than a request to IT.
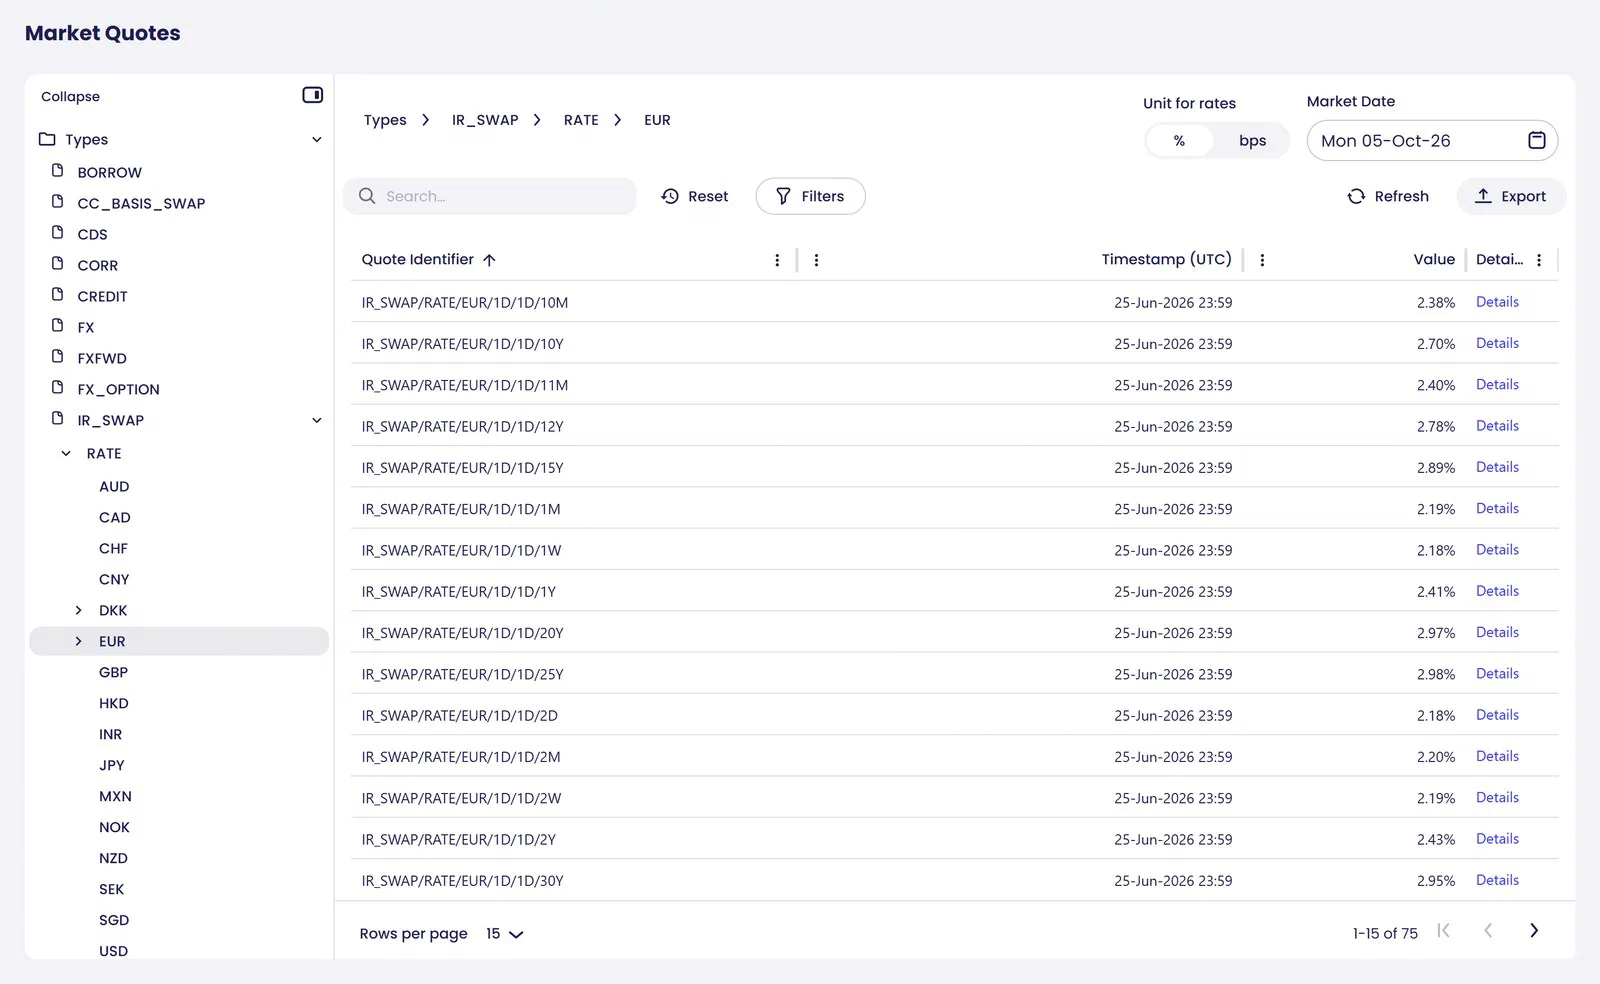
Regulatory numbers must reconcile to your official curves, vols and spreads. Norma ingests them through a published input specification and checks them for completeness and consistency on import. Hosted clients pass their own data entitlements through.
Hosted in a single tenant in a UK or EU region, containers in your own cloud tenancy, or on-prem. In your tenancy your own controls apply.
Norma started with XVA because it is the hardest calculation in the risk stack: every trade, every counterparty, thousands of market scenarios, valued together over the life of the book. An engine that does XVA live has solved pricing, exposure and capital on the way.
Import curves, quotes and surfaces by type and market date, checked on import for completeness and consistency, with history per quote.
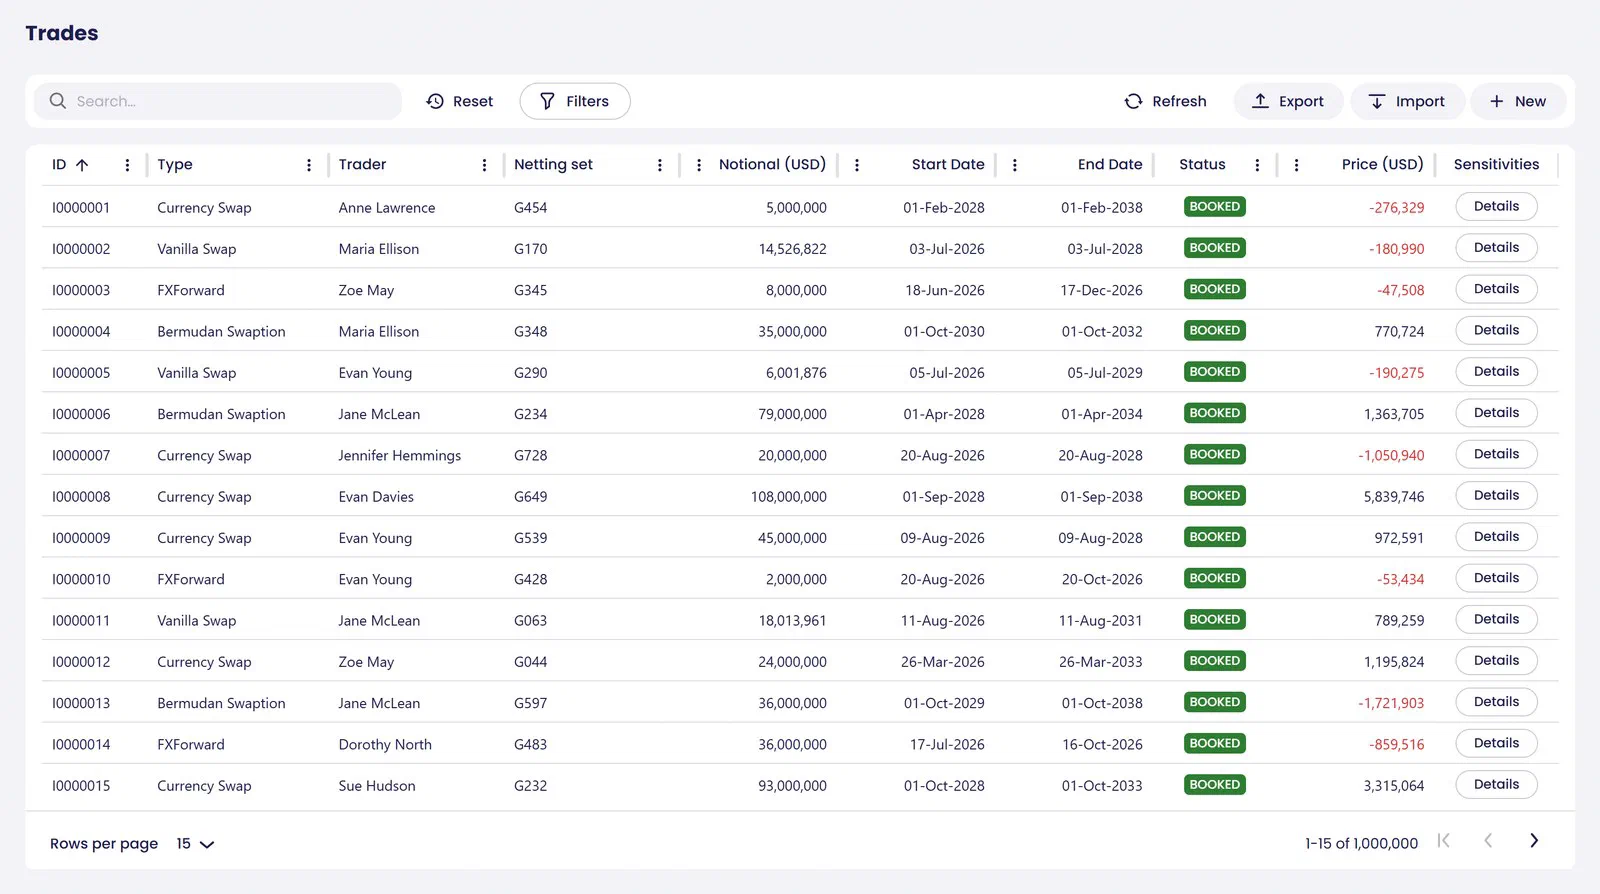
A million-trade book across products by netting set, with price and sensitivities per trade, and netting sets and counterparties alongside.
Norma is not a trading system; it runs beside the front-office platform. It is not a black box: every number is transparent down to the trade in the analytics dashboards.