Request a demo

Norma Pricing

The XVA impact of a trade,
before it is booked.

The XVA, initial margin and lifetime capital impact of a new trade, with Greeks, in under a second, before it is booked. On the same models and market data as your end of day.

< 1 s
XVA impact of a new trade, with Greeks
Incremental CVA, DVA, FVA and KVA on the netting set, with full sensitivities
< 1 min
full XVA run with full sensitivities, 1M-trade portfolio
Every XVA, the exposures, a million first-order sensitivities and hundreds of thousands of second-order, from one run; no overnight batch
Any product
vanilla and exotic, across asset classes
Plus custom scripted payoffs, priced on the same engine with the same market data

Where it fits

Until now the XVA on a quote was a call to the XVA desk, answered from last night's run, and the capital was a rule of thumb. Both are now in the price, computed on the netting set as it stands.

Sales desks

Electronic pricing across all asset classes with XVA, initial margin and KVA included, without waiting for the XVA desk.

XVA desks

Live XVA and hedging sensitivities under current market conditions, and the capital a new trade adds to the netting set, before it is booked.

Beside your platform

Runs next to your front-office platform or in-house engine as the fast path for pre-trade and intraday. No migration.

Pricing, trade by trade

Enter the trade, see the price

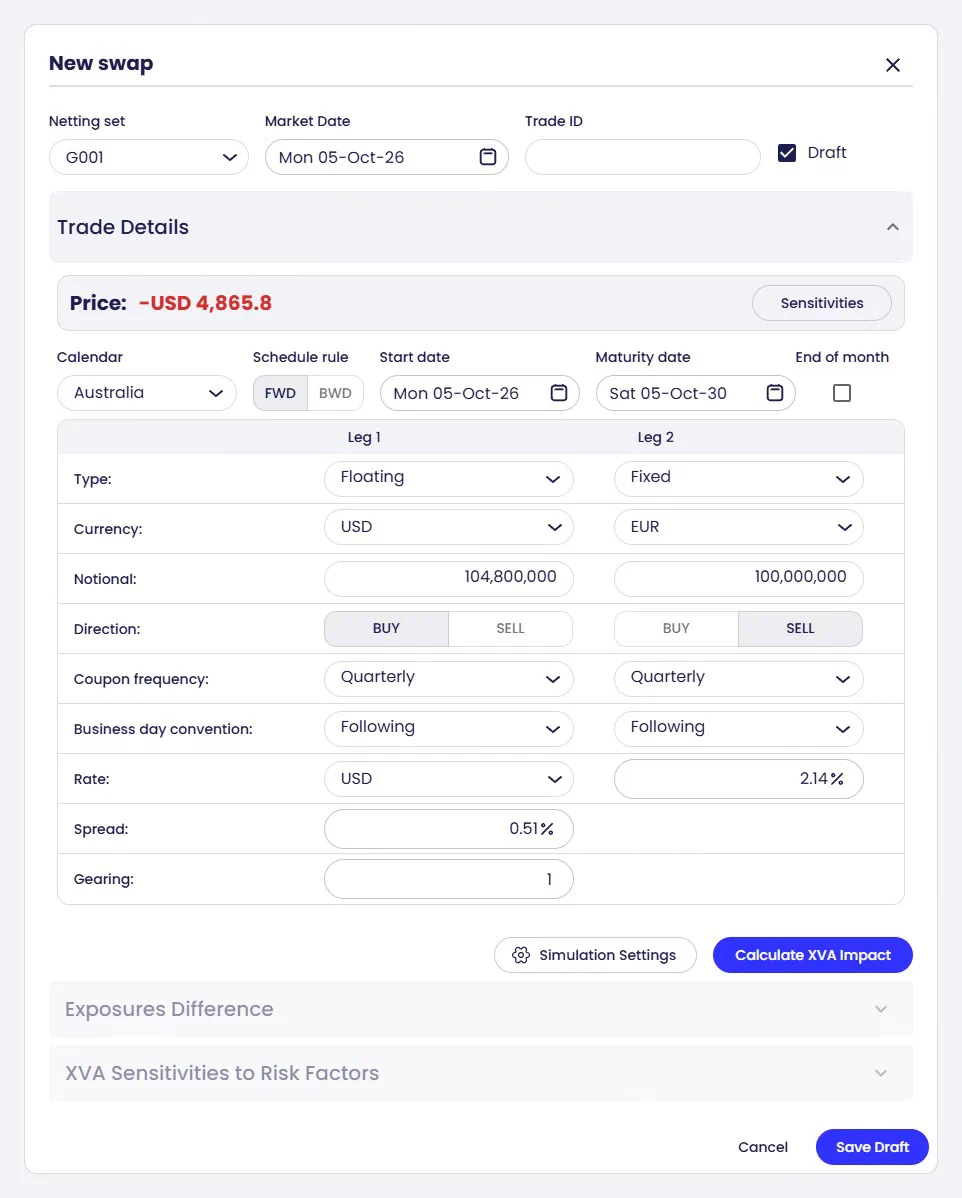
A new swap entered leg by leg, priced immediately, with sensitivities on the button. Calculate the XVA impact before it is booked.

  • Price and Greeks in under a second
  • Option flow as well as linear
  • In the analytics dashboards, or via the API into your own reporting
Request a demo
Enter a new swap leg by leg, see its price straight away, and calculate its incremental XVA impact before saving it as a draft or booked trade

The quote carries the capital

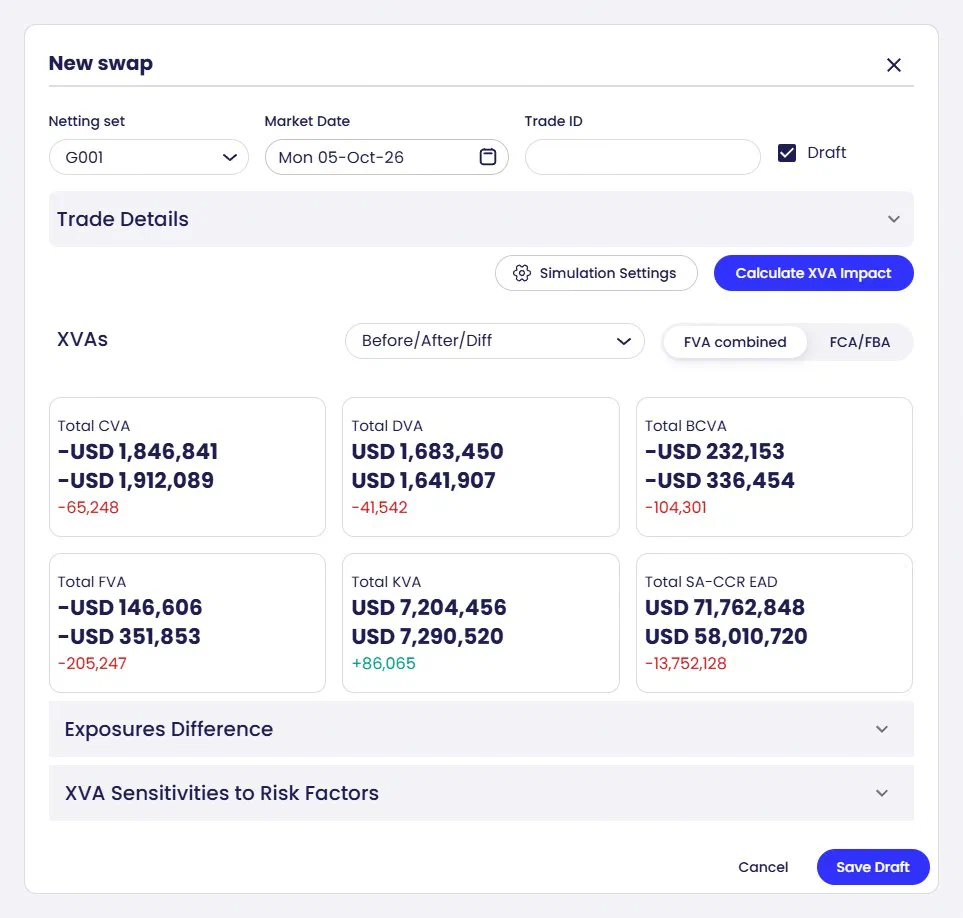
Every XVA and the SA-CCR exposure on the netting set with and without the trade, and the exposure difference over its life.

  • Incremental to the netting set
  • CVA, DVA, BCVA, FVA, MVA, ColVA, KVA, SA-CCR EAD
  • Same models and data as end of day
Norma Capital
Before, after and difference for CVA, DVA, BCVA, FVA, KVA and SA-CCR EAD when the new trade is added to the netting set

Greeks the desk can hedge from, and the P&L explained

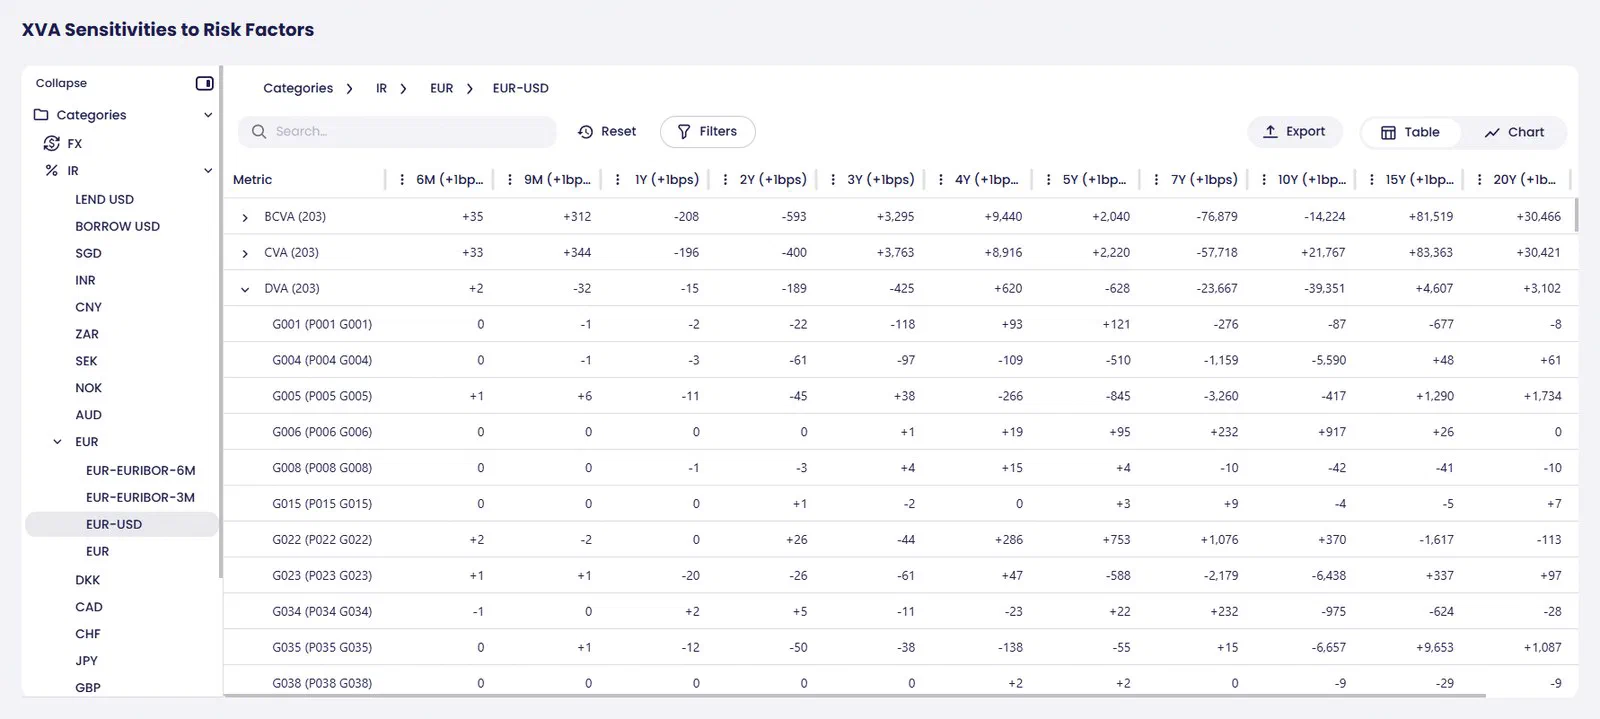
Delta by netting set, currency and index, gamma and cross-gamma by risk-factor pair, from the same run that priced the trade. Day-on-day XVA P&L explained by market moves, time, trades, credit and reference data.

  • Per netting set and currency
  • P&L explain by netting set
  • Exportable to the desk's tools
Benchmarks
XVA sensitivities grouped by FX, interest rate and credit risk factors, with drill-down to individual curves and netting sets, as a table or a chart

Before and after, across the book

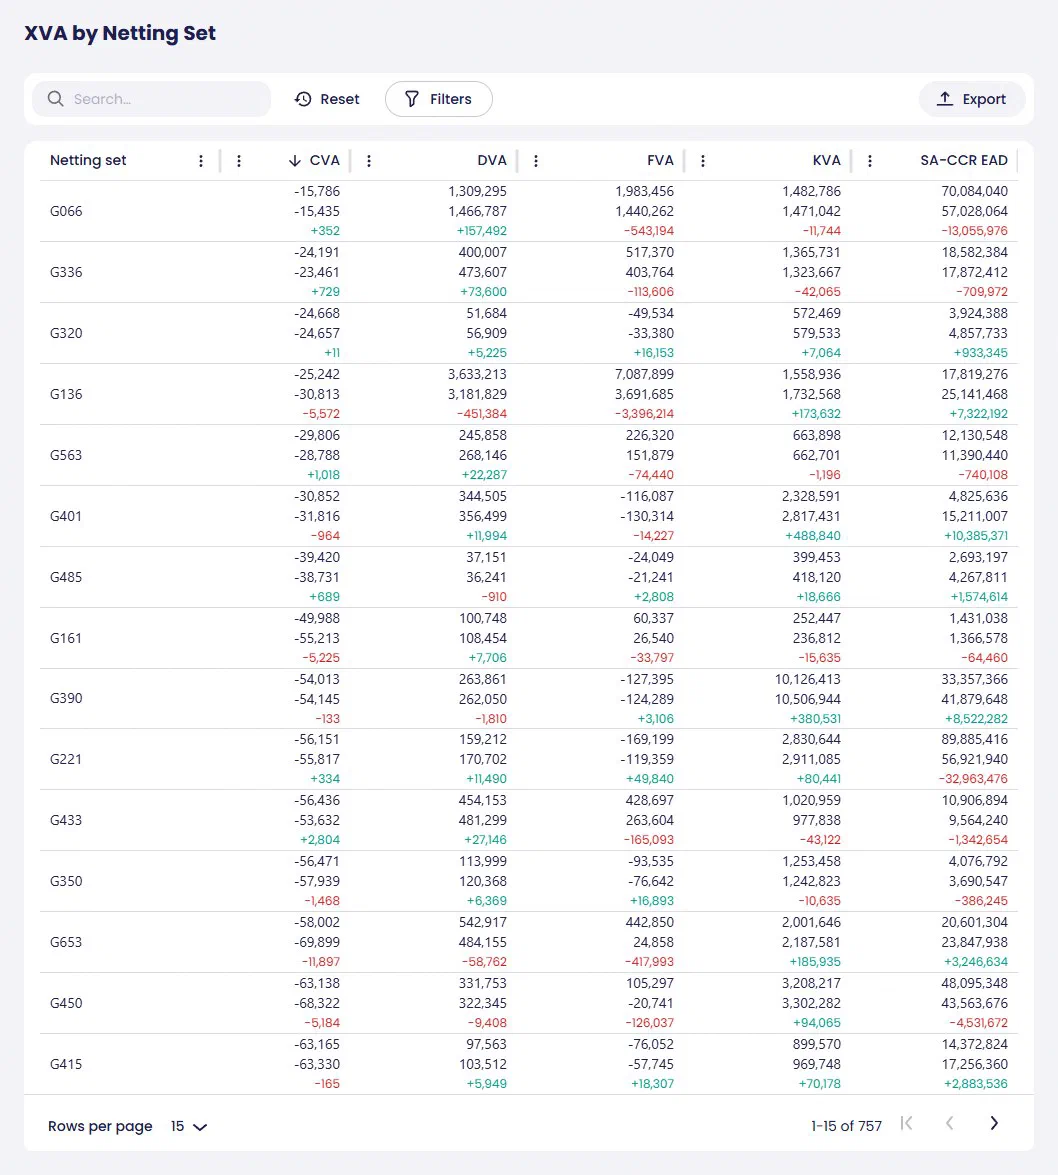
What-if by netting set: before, after and difference for each XVA, with the largest moves charted, so a large trade or an unwind is priced against its real effect.

  • Novation and partial unwind
  • Counterparty choice by incremental capital
  • Intraday, no batch
Norma Exposure
XVA figures per netting set, showing the base run, the what-if run and the difference for each measure

Initial margin, and what it costs

Initial margin under ISDA SIMM per netting set, pre-trade and on the book, and MVA, the lifetime cost of posting it, in the same run as CVA, FVA and KVA. ColVA, the value of the CSA terms themselves, so the quote reflects the collateral rate and thresholds actually agreed. Exposure profiles with and without margin, so a collateralised quote is priced on the exposure that remains.

API or analytics dashboards

Work in Norma's analytics dashboards, or integrate the REST API into your own workflow and screens, deployed in your cloud tenancy or on-prem. Same engine, same numbers, same market data as your end-of-day.

See it on your own trades.

Request a demo

Get in touch

Request a demo on your own trades, or just talk to us.